IRR
The Internal Rate of Return (IRR) is the discount rate that delivers a Net Present Value (NPV) of zero for a series of future cash flows. It is an Discounted Cash Flow approach to valuation and investing. IRR and NPV are widely used to decide which investments should be undertaken, and which investments not to make. The IRR can be calculated by trial and error using the following expression:
+


If the IRR is bigger than the cost of capital (WACC) then an investment decision can be accepted.
Be aware of the difference of a Project IRR and an Equity IRR. The project IRRs consider the project cash flows before considering funding, with initial negatives equal to construction costs, and later positives from the net operating cash flows, and gives a measure of the general strength of the project.
The equity or investor IRRs are calculated on the relevant cash flow to investors, with payments from investors (pure equity paid in, drawings on sub debt etc) as initial negatives, and payments to investors (dividends, payments to sub debt etc. as appropriate) as positives.
When presenting IRR in a business plan make sure that the difference between investor IRR and project IRR is clearly articulated
The discount rate often used in capital budgeting that makes the net present value of all cash flows from a particular project equal to zero. Generally, the higher a project's internal rate of return is, the more desirable it is to undertake. Thus, IRR can be used to rank potential projects. Assuming all factors are equal, the project with the highest IRR probably would be considered the best and would be undertaken first. IRR sometimes is referred to as the economic rate of return (ERR). The IRR has the following pitfalls:
1) Lending or borrowing
No all cash flow streams have NPV's that decline as the discount rate increases. In the following example based on IRR both projects are equally attractive:
| Project | \[C_0\] | \[C_1\] | IRR | NPV at 10% |
|---|---|---|---|---|
| A | ||||
| B | 1000 |
2) Multiple rates of return
In certain cases the formula for IRR can result in two solutions. 3) Mutually exclusive In case where multiple options exists a higher NPV is better than a higher IRR.
| Project | \[C_0\] | \[C_1\] | IRR | NPV at 10% |
|---|---|---|---|---|
| D | ||||
| E |
In the case of project 'D' you have a 100% rate of return, in the case of project 'E' you are \$11818,- richer (~3M more than project 'D')
4) The cost of capital for near term cash flows may be different than the cost of capital for future cash flows If we look again at the formula for NPV: The IRR rule says to accept a project if the IRR is greater than the cost of capital (represented by , etc). But what to do if you have different values for ? If you assume the will not change and it increases than you may have been too optimistic in accepting the project.


See also this
example for comparison:
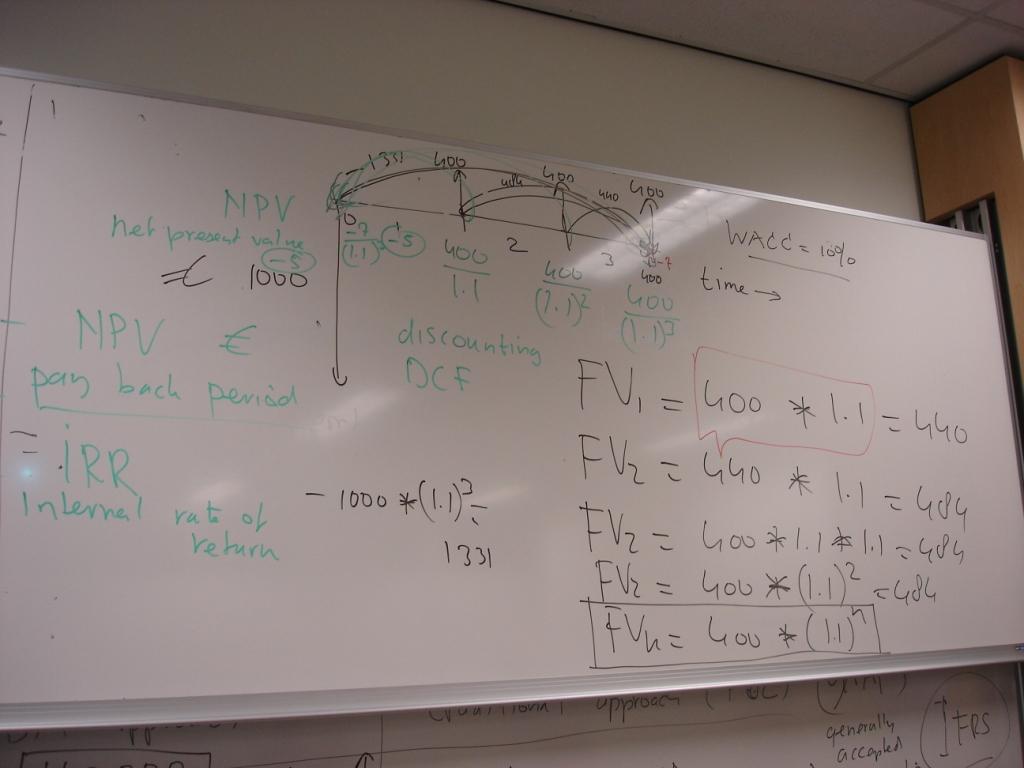
And the picture on the board during the M9-Accounting block: