Portfolio Theory and the Capital Asset Pricing Model
Jump to navigation
Jump to search
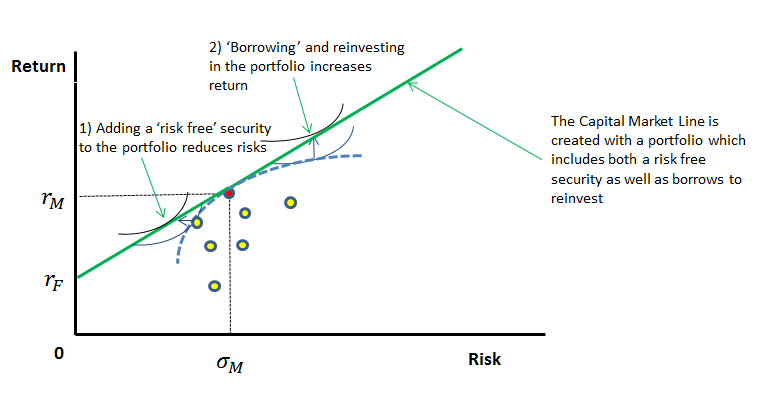
The picture below depicts a set of possible investment portfolios. The risk of a portfolio comprises systematic risk, also known as Undiversifiable Risk, and unsystematic risk which is also known as Diversifiable Risk, usually proxied by the standard deviation of the portfolio's return. Undiversifiable risk refers to the risk common to all securities which is the market risk.
- is the average market risk
- is the average variance on the market risk
- is the Risk free rate of return
- The red dot in the picture marks the full market portfolio
- The Efficient set (the blue line) represents the biggest return possible for each given risk profile


The CAPM assumes that the risk-return profile of a portfolio can be optimized - an optimal portfolio displays the lowest possible level of risk for its level of return.
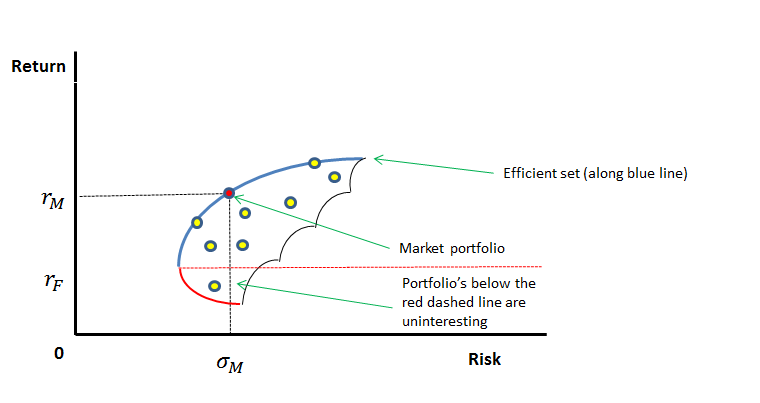
By adding a risk free asset to a portfolio, one can reduce risk:
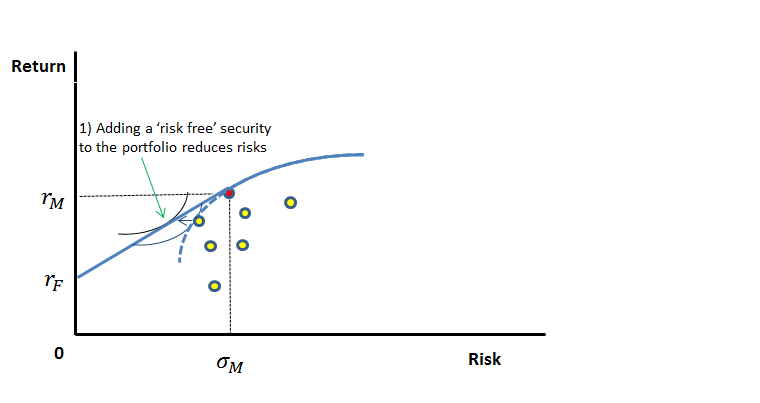
By borrowing and increasing your portfolio you can increase return:
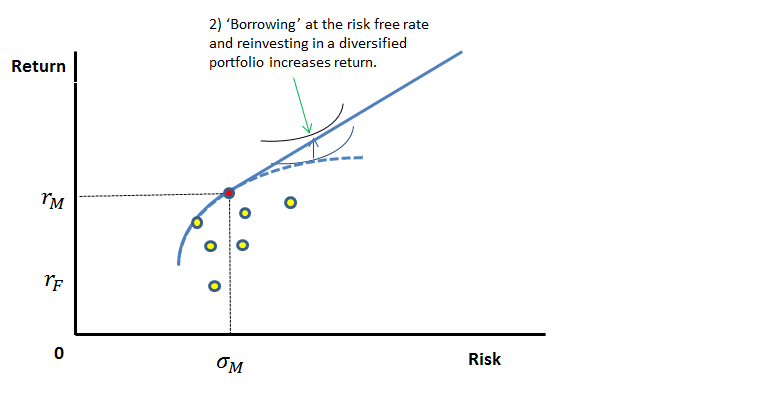
By doing both 1) and 2) we get the Capital Market Line: