Options
In finance two different interpretations for options exist:
- Financial Options as found in the financial markets
- Real Options which are an attempt to apply similar concepts to entrepreneurial project and financial decisions.
When mapping project characteristics onto call option variables you can see the following similarities:
| Project | Variable | Option |
|---|---|---|
| Expenditures required to acquire the asset | Exercise price | |
| Value of the operating assets to be acquired | Stock price | |
| Length of the time decision may be defered | Time to experation | |
| Riskiness of the underlying operating assets | Variance of returns on stock | |
| Time value of money | Risk free rate of return |


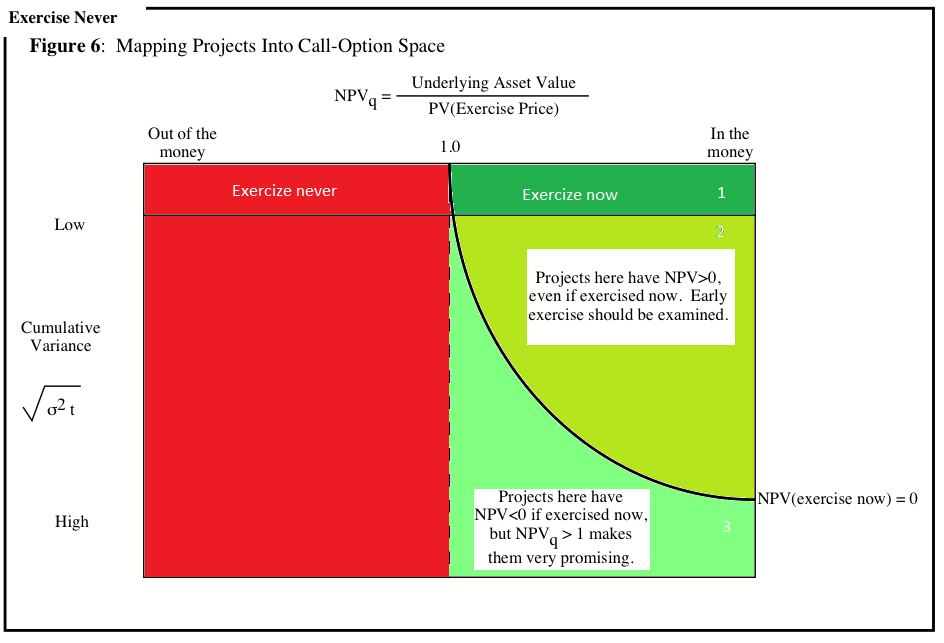
When a decision cannot be delayed standard DCF techniques as NPV or NPV_q are sufficient to model the decision. However if the decision can be delayed, the project is more like an option and also will need to take the riskiness of the project into account.
A very simple summary of using real options as an approach for investment decisions is:
- Use DCF, NPV or IRR in most cases.
- Only for projects for which have very good data and estimates of how risk accummulates over time a real option approach may be applicable.
The riskiness is represented by the remaining option variable . The variability, per unit time, of the project is represented by the variance of the returns, . Cumulative variance is a measure of how things could change over time and represented as