Difference between revisions of "M9-S4 - Activity based costing"
| Line 1: | Line 1: | ||
| − | + | {{:Activity based costing}} | |
| + | |||
| + | The ABC paradox is that even though the obvious advantages of activity based costing, it is not widely adopted yet. The major reason is that it is tedious to do. With [[Time-Driven Activity Based Costing|Time-Driven Activity Based Costing]] the amount of labor overhead to introduce ABC can be reduced but as it depends on asking people how much time they spend on activities, it is not that reliable. | ||
[[Category:mbi]] | [[Category:mbi]] | ||
Latest revision as of 20:00, 27 August 2020
Activity Based Costing (ABC) is an alternative to the traditional way of accounting Traditionally it is assumed that high volume customers are profitable customers. A loyal customer is also a profitable customer. And profits will follow a happy customer. Studies about customer profitability have unveiled that the above ideas are not necessarily true. ABC is a costing model that identifies the cost pools, or activity centers, in an organization. It assigns costs to products and services (cost drivers),based on the number of events or transactions that are taking place in the process of providing a product or service. As a result, Activity Based Management can support managers to see how shareholder value can be maximized and how corporate performance can be improved.
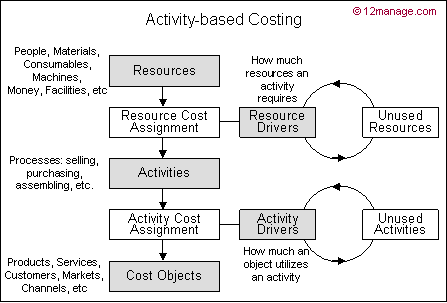
Typical benefits of Activity-Based Costing:
- Identify the most profitable customers, products and channels.
- Identify the least profitable customers, products and channels.
- Determine the true contributors to- and detractors from- financial performance.
- Accurately predict costs, profits and resources requirements associated with changes in production volumes, organizational structure and costs of resources.
- Easily identify the root causes of poor financial performance.
- Track costs of activities and work processes.
- Equip managers with cost intelligence to stimulate improvements
- Facilitate a better Marketing Mix
- Enhance the bargaining power with the customer.
- Achieve better Positioning of products
The ABC paradox is that even though the obvious advantages of activity based costing, it is not widely adopted yet. The major reason is that it is tedious to do. With Time-Driven Activity Based Costing the amount of labor overhead to introduce ABC can be reduced but as it depends on asking people how much time they spend on activities, it is not that reliable.
