Difference between revisions of "Hamada formula"
Jump to navigation
Jump to search
(Replaced content with "Hamada formula Category:finance Category:M12 Category:Term") Tag: Replaced |
|||
| Line 1: | Line 1: | ||
| − | + | [[Levered Beta|Levered Beta]] is the beta that reflects a capital structure that does include debt. | |
| + | The [[Unlevered Beta|Unlevered Beta]] is the [[Beta|Beta]] of a company without any debt. Unlevering a beta removes the financial effects from leverage. | ||
| + | |||
| + | |||
| + | |||
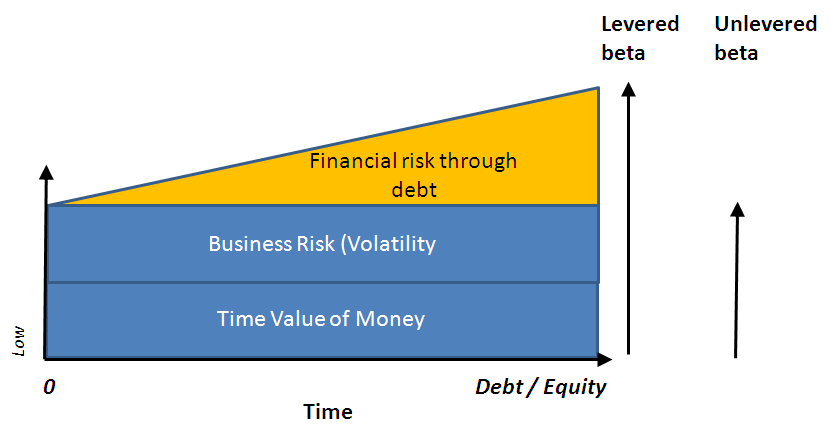
| + | <html><img src = "/static/files/MBI/Module%2012/leveredbeta.PNG" width="600"/></html> | ||
| + | |||
| + | |||
| + | |||
| + | <math> \text{Unlevered beta}</math> = <math>\frac{B^L}{1+(1-T_c)*\frac{D}{E}}</math> | ||
| + | |||
| + | Where: | ||
| + | * <math>{B^L}</math> is the levered, published beta | ||
| + | * <math>{D}</math> is the companies debt | ||
| + | * <math>{E}</math> is the companies equity | ||
| + | * <math>{T_c}</math> is the corporate tax rate. | ||
| + | |||
| + | ==+ The point of the unlevered beta is to ''''remove'''' the debt risk from a publicly known company in a sector comparable to your own company ('unlever the beta') add your own debt risk and 'lever' the beta.== | ||
| + | |||
| + | |||
[[Category:finance]] | [[Category:finance]] | ||
Latest revision as of 19:24, 27 August 2020
Levered Beta is the beta that reflects a capital structure that does include debt. The Unlevered Beta is the Beta of a company without any debt. Unlevering a beta removes the financial effects from leverage.
=


Where:
- is the levered, published beta
- is the companies debt
- is the companies equity
- is the corporate tax rate.


