Difference between revisions of "Cash conversion cycle"
(Created page with "In management accounting, the Cash Conversion Cycle (CCC) measures how long a firm will be deprived of cash if it increases its investment in resources in order to expand cust...") |
|
| (One intermediate revision by the same user not shown) | |
(No difference)
| |
Latest revision as of 19:23, 27 August 2020
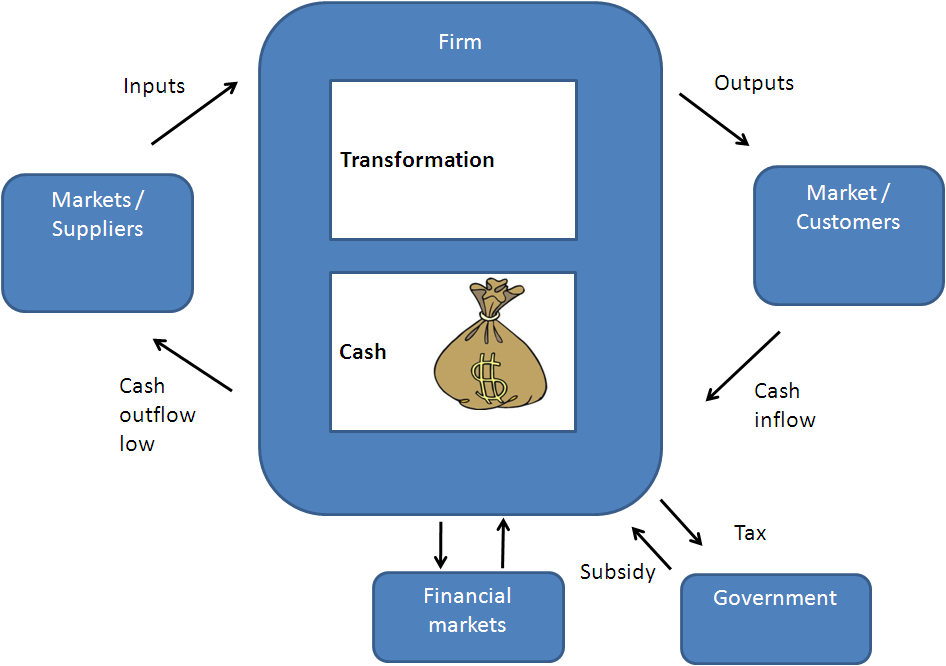
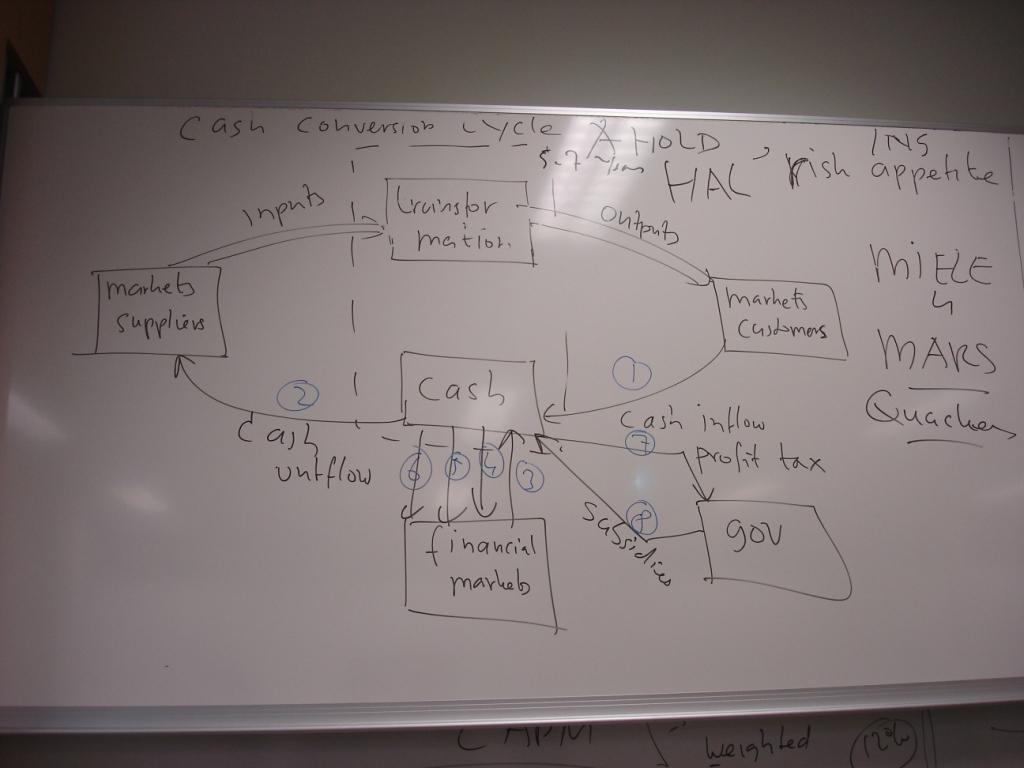
In management accounting, the Cash Conversion Cycle (CCC) measures how long a firm will be deprived of cash if it increases its investment in resources in order to expand customer sales. It is thus a measure of the liquidity risk entailed by growth. However, shortening the CCC creates its own risks: while a firm could even achieve a negative CCC by collecting from customers before paying suppliers, a policy of strict collections and lax payments is not always sustainable.
{{{
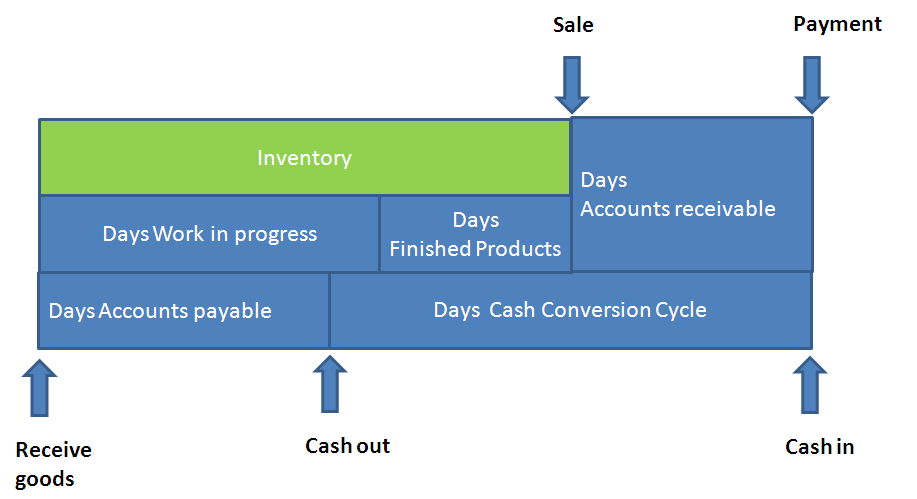
CCC = # days between disbursing cash and collecting cash in connection with undertaking a discrete unit of operations.
= Inventory conversion period + Receivables conversion period – Payables conversion period = Avg. Inventory COGS / 365 + Avg. Accounts Receivable Credit Sales / 365 – Avg. Accounts Payable COGS / 365 }}}